02 Oct 2026
Rising energy prices and renewed inflation risks have prompted markets to price in further rate hikes across several developed economies. Mike Riddell, Lead Portfolio Manager of the Fidelity Strategic Bond Fund, explains why, while markets may be pricing too much tightening, growing pressure at the long end of bond markets calls for a more selective approach.
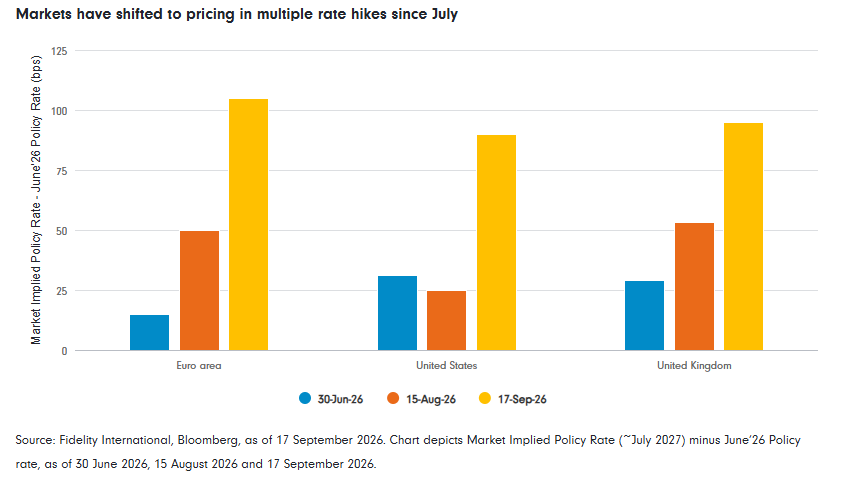
We reduced overall duration exposure as higher energy prices and rising inflation expectations could lead to further policy tightening.
Duration exposure was reduced across several markets including the US, UK, Italy, Canada and Korea as long-end bond yields in major developed markets moved higher and supply pressures intensified.
We still believe markets are pricing too many hikes across several developed economies, however we now prefer to express this view towards the front end of the curve, through yield-curve steepeners.
Within emerging markets, we took profits in Colombia following strong performance and subsequently exited the remaining Brazil and Mexico rates exposure.
Inflation data has generally behaved better than expected in recent months, helped by well contained food inflation and limited evidence of broader second-round effects.
However, we have become increasingly cautious that markets may be underestimating the inflationary impact of higher energy prices. Brent crude has continued to move higher while gas and electricity prices have also risen sharply.
We therefore continue to retain inflation protection, particularly in the US, where medium-term inflation expectations still appear relatively contained compared with the upside risks from energy and commodity markets.
We shifted towards a more defensive currency stance by reducing emerging market currency exposure as market volatility increased the risk of a stronger US dollar.
We booked profits on our remaining Brazilian real position ahead of Brazil's presidential election in October. We also exited our Chilean peso exposure as the currency remains sensitive to rising energy prices.
We retained conviction in the Norwegian krone, Colombian peso and Swiss franc, while maintaining our short Japanese yen position. Meanwhile, we closed our long euro position and reallocated exposure towards the Swedish krona and British pound.
We continue to maintain a cautious stance in credit, as valuations remain unattractive and spreads offer limited compensation should growth or risk sentiment weaken. Despite higher energy prices, government bond volatility and continued geopolitical uncertainty, credit spreads remain close to historically tight levels. We therefore see limited value in adding broad credit risk at current valuations.
Past performance does not predict future returns
| Standard period fund performance* (GBP, gross of fees) | 1 month | 3 months | 6 months | 12 months |
|---|---|---|---|---|
|
Fidelity Strategic Bond * |
-0.2% |
-0.4% |
0.7% |
2.9% |
|
Index** |
0.1% |
-0.5% |
-1.4% |
1.7% |
12-month rolling returns gross of fees, GBP (%)
|
31.08.16- 31.08.17 |
31.08.17- 31.08.18 |
31.08.18- 31.08.19 |
31.08.19- 31.08.20 |
31.08.20- 31.08.21 |
31.08.21- 31.08.22 |
31.08.22- 31.08.23 |
31.08.23- 31.08.24 |
31.08.24- 31.08.25 |
31.08.25- 31.08.26 |
|
|
Fund |
0.9% |
-0.8% |
8.3% |
6.0% |
5.2% |
-15.0% |
0.0% |
10.7% |
5.1% |
2.9% |
|
Index |
1.5% |
-0.3% |
8.3% |
2.6% |
3.5% |
-12.8% |
1.3% |
9.5% |
3.8% |
1.7% |
Source: Fidelity International, Bloomberg, 31 August 2026. *Performance reflects W Income shares (gross of fees). Ongoing Charges Figure of 0.64% per year applies. **Index and relative returns reflect the Strategic Asset Allocation Blend (ICE BofA Q880 Custom Index) until 01 December 2024 and thereafter Bloomberg Global Aggregate Index Total Return Index Hedged to GBP. Fund inception: 18 April 2005. Performance data is quoted at the fund's official valuation point. Please also note that numbers may not sum exactly to totals shown due to the rounding of figures.
Important information
This information must not be reproduced or circulated without prior permission. This information does not constitute investment advice unless specifically agreed in a formal communication. Fidelity International refers to the group of companies which form the global investment management organisation that provides information on products and services in designated jurisdictions outside of North America. Unless otherwise stated all products and services are provided by Fidelity International, and all views expressed are those of Fidelity International. Fidelity, Fidelity International, the Fidelity International logo and F symbol are registered trademarks of FIL Limited. FIL Limited assets and resources as at 31/08/2026 - data is unaudited. No statements or representations made in this document are legally binding on Fidelity or the recipient. Any proposal is subject to contract terms being agreed. Fidelity Investment Funds, Fidelity Investment Funds 2, Fidelity Investment Funds III, Fidelity Investment Funds IV and Fidelity Investment Funds IX are open-ended investment companies (OEICs) with variable capital, incorporated in England and Wales, being authorised and regulated by the Financial Conduct Authority. The Authorised Corporate Director of these OEICs is FIL Investment Services (UK) Limited. Data Source - © 2024 Morningstar, Inc. All Rights Reserved. The information contained herein: (1) is proprietary to Morningstar and/or its content providers; (2) may not be copied or distributed; and (3) is not warranted to be accurate, complete or timely. Neither Morningstar nor its content providers are responsible for any damages or losses arising from any use of this information.
This communication is not directed at, and must not be acted upon by persons inside the United States and is otherwise only directed at persons residing in jurisdictions where the relevant funds are authorised for distribution or where no such authorisation is required. We recommend that you obtain detailed information before taking any investment decision on the basis of the current prospectus and KIID (key investor information document), as applicable. These documents, the current annual and semi-annual reports are available in English and can be obtained from our website at www.fidelityinternational.com.
UK: The Key Investor Information Document (KIID) is available in English and can be obtained from our website at www.fidelityinternational.com. The Prospectus may also be obtained from Fidelity. Issued by FIL Pensions Management. Authorised and regulated by the Financial Conduct Authority.
FIPM: 10843